Sonar sits across all of UNIFOS. It screens digital payments and card spend on the issuing side, every merchant and agent payment on the acquiring side, and every loan before it is disbursed, in real time, before money moves, and always on your own rules. Every night it looks back across 30 days of money in and out and turns laundering patterns into cases for your compliance team.
Unified Financial Operating System for Banks
Sonar · One Fraud and Risk Engine for Every Payment Made or Accepted, and Every Loan

SonarFraud & Risk Management
- ~60
- rules on every payment, in real time
- 3
- outcomes: decline, second factor or alert
- 30 days
- of money in and out reviewed every night
- 1 floor
- of compliance rules no bank can switch off
One Engine Watching All the Money That Moves
Transfers, ScanPay, cards online and in store, agent cash and merchant sales: one engine screens them all, in real time, before money moves.
Nearly 60 rules run on every payment, and their scores add up. One weak signal lets a good customer through; several together act.
A compliance floor of sanctions, deny lists and sanctioned countries stops payments on every channel, and no bank can switch it off.
Every night, money in and out over the last 30 days is checked for laundering patterns, and each one becomes a case.
Every bank starts on our recommended defaults and tunes them within safe ranges on the Partner portal.
Every Payment Checked, Three Clear Outcomes
Every rule adds to one risk score. Why a payment is flagged, and where it is made, decides what happens next.
DeclineCompliance
Declined when the law says no
- Deny lists, sanctions name matches, sanctioned countries and the shared blacklist.
- Politically exposed persons and high-risk jurisdictions.
- On every channel, card present too. No bank can switch this floor off.
Step-upRisk on digital payments
Confirmed with a second factor, not refused
- A step-up is second-factor authentication: after the PIN, the customer enters the code from their Verifyed soft token app.
- A good customer confirms and the payment books, with no second screen.
- A fraudster holding only the PIN is stopped there.
AlertRisk on card present
Approved, with an alert to your team
- At POS, SoftPOS, ATMs and agents, the physical card and its PIN prove the customer.
- A risky card-present payment is approved and your team gets an alert.
- Compliance hits are still declined at the counter.
Families of Rules, Ready on Day One
Nearly 60 rules, each with a recommended default and a safe range, so protection starts the day you go live and fits your book as it grows.
01
Amount and velocity
- Large single payments
- Too many or too much in minutes
- Too many in a day
- Sudden bursts at once
- Far above the customer’s own usual amount
ActionStep-up: second factor (Verifyed code)
02
Payee
- New payee at value
- Same amount repeated
- Same merchant again and again
- Payee name mismatch
- Beneficiary details changed
- Push-payment scams
ActionStep-up: second factor (Verifyed code)
03
Account takeover
- New device
- Impossible travel
- SIM swap
- Dormant account wakes up
- Alert number changed
- Limit raised, then a big payment
ActionStep-up: second factor (Verifyed code)
04
Laundering and mules
- Split payments
- Just under a threshold
- Money in, then out fast
- Mule fan-in
- High-risk country flows
ActionSecond factor and a case, never a decline
05
Cards
- Card testing
- PIN abuse
- Online card mismatch
- Local card used abroad
- Betting, forex and crypto
- Prepaid or virtual card drained fast
ActionVerifyed code online, alert in store
06
Agents and merchants
- Agent daily and weekly cash caps
- Agent cash-out splitting
- Card cycling across agents
- Split sales
- Merchant-side card testing
ActionAlert to your team; regulatory cash caps decline
Every night
Money In and Out, Watched Every Night
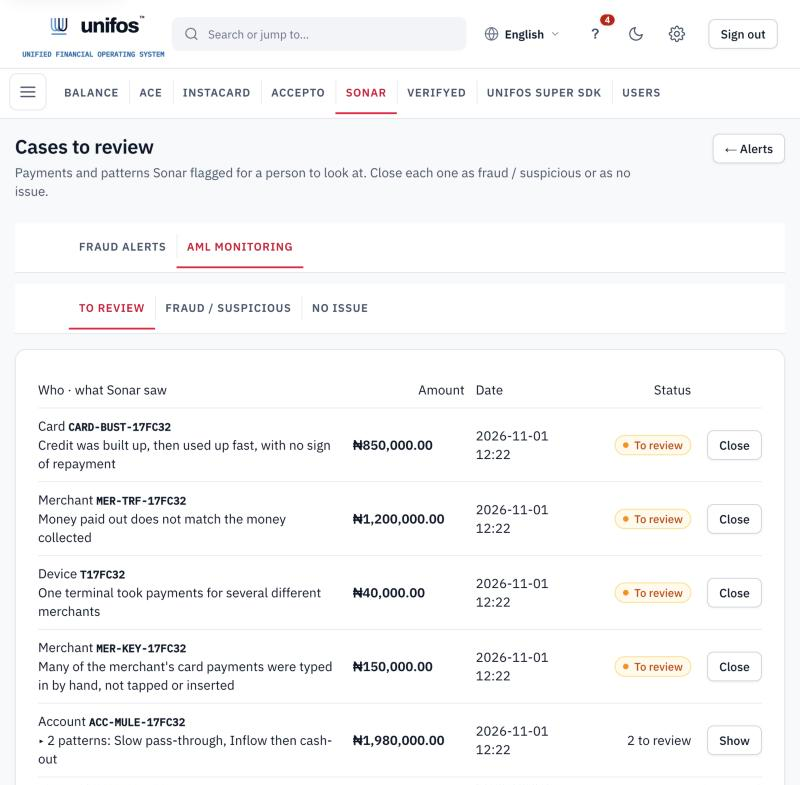
Some fraud only shows over time. After the day closes, Sonar looks back across up to 30 days of activity, including money that arrived from other banks, and opens a case for every pattern it finds. No payment waits for it.
Laundering patterns
Split paymentsMule fan-inPass-through accountsMoney in, then out as cashRecall after spendingSpend far above the usual, festive-season awareMerchant chargeback and refund ratiosMerchant volume spikesKeyed-in card salesTerminals shared by merchantsCommon point of purchaseCredit-card bust-out
Counterparty screening
Every new payee and sender at another bank is checked once against the UN, OFAC, UK, EU and local sanctions lists, PEP data and your own watchlist. A confirmed hit goes on the deny list, and the next payment to it is stopped in real time.
Cases your team decides
Each case is closed as no issue, escalated as a suspicious transaction report, sent to the watchlist so the next payment asks for the second factor, or added to the deny list, by a maker and a checker. Sonar never freezes an account on its own.
Your Rules, Your Thresholds, Your Sign-Off
Your risk and compliance teams run Sonar from the Partner portal: rules, alerts, cases and lists in one place.
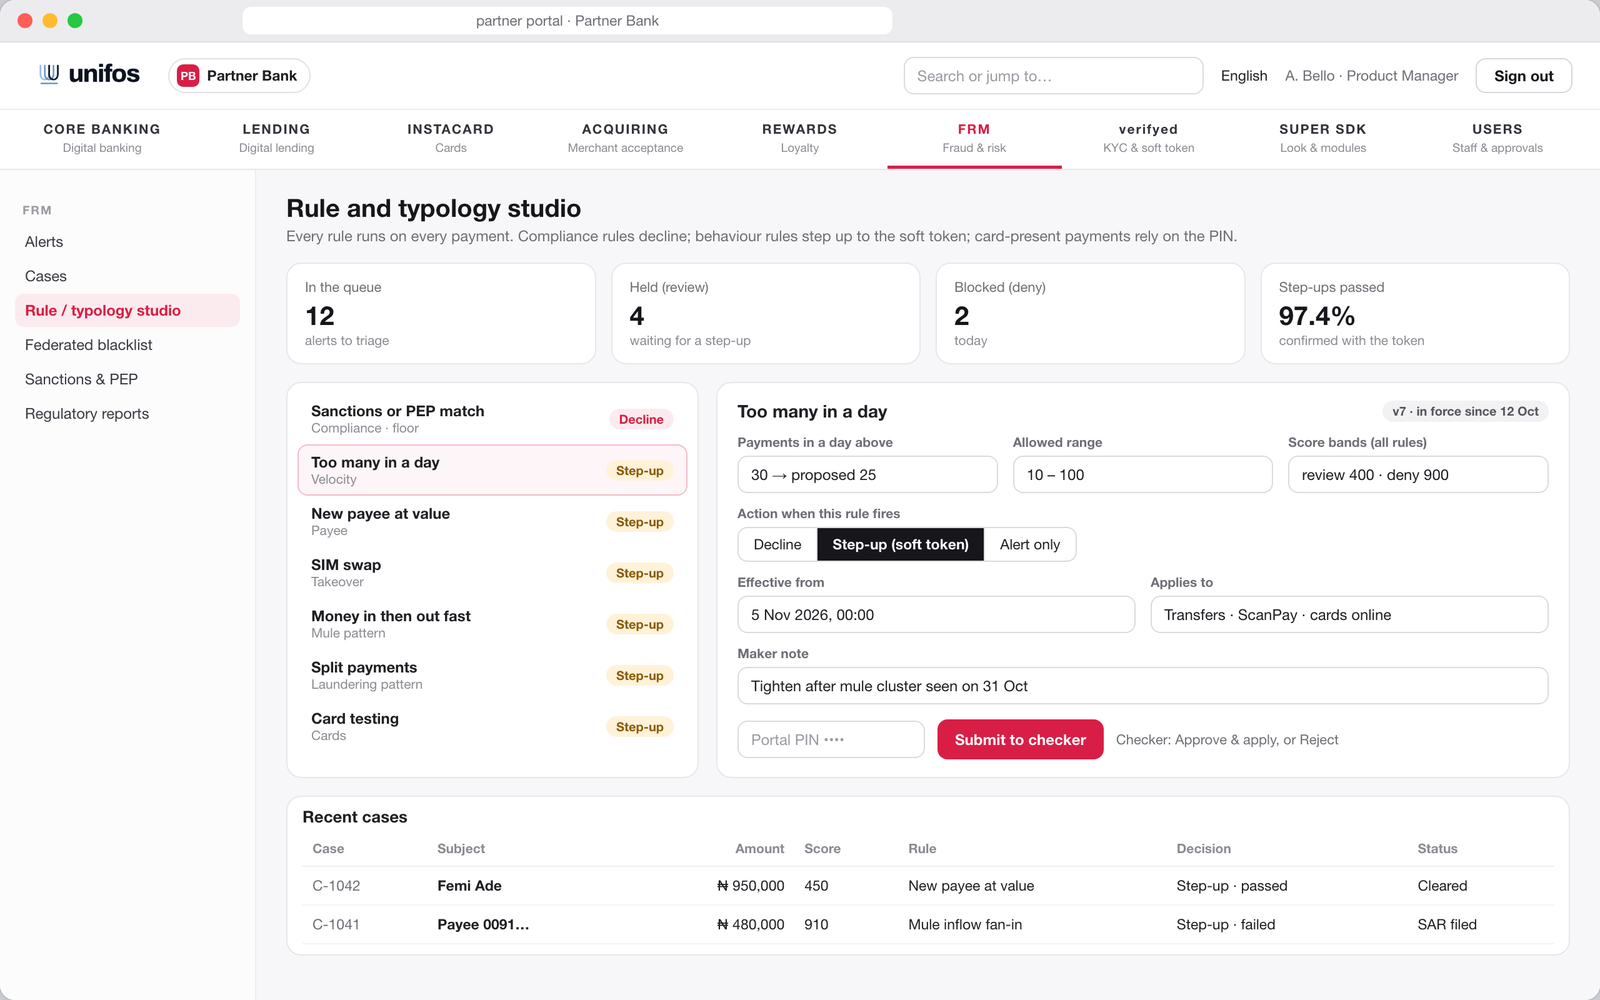
Your action, rule by rule
Choose a step-up to second-factor authentication, or alert only, for each risk rule. Compliance rules always decline, and laundering rules never do.
Your thresholds
Tune each value within its allowed range, choose the payments it covers and the date it takes effect.
Your score bands
Set the total score at which a payment is held for review, and the one at which it is declined.
Maker-checker and a portal PIN signature on every change
A maker proposes a change and signs it with the UNIFOS portal PIN. A second person sees the old and new values, then approves or rejects it, signing too.
Lists and screening
Keep your own deny list and watchlist, alongside the shared blacklist and sanctions and PEP screening.
Lasting Value for Banks Across Africa
Fraud is stopped before the money leaves, not chased after it.
Good customers confirm and carry on, instead of calling to ask why a payment failed.
Your compliance team gets a sanctions floor, nightly AML monitoring and a case queue ready for regulatory reporting.
Explore Other Products
- Verifyed · KYC & Soft Token
- KYC management
- Liveness detection and face match
- BVN, NIN and ID verification
- Business and address verification
- Soft token issuance for 2FA
- BALANCE · Digital Banking
- Digital and business accounts
- Credit card and prepaid card accounts
- Loan accounts
- Reward points and redemption accounts
- ScanPay · Pay by QR
- Any merchant’s interoperable QR, any bank
- Static and dynamic QR codes
- Instacard, BALANCE account or another bank’s card
- Checkout on merchant sites
- Accepto · Merchant Acceptance
- SoftPOS for contactless payments
- POS terminals
- Payment links and online checkout
- Digital business accounts for settlement
- Instacard · Virtual & Universal Cards
- Virtual and physical card issuance
- Debit, credit, prepaid and gift cards
- Universal card
- Dynamic CVV for online payments
- Contactless payments with virtual cards
- Ace · AI Credit Exchange
- Three-way underwriting with an AI Checker
- Loan and credit card origination
- Portfolio management
- Collections and repayments
- DTS · Dual Transaction Service
- Virtual credit cards
- Credit on existing debit cards
- Collections and repayments
- Dynamic limit management
- Fundu · Agency Banking
- Cash deposits and withdrawals
- Bills, airtime and data
- Universal card pick-up
- Verified agents only
- Guida · In-App Assistant
- Understands requests in multiple languages
- Guides customers through every product
- Tickets for disputes, tracked to resolution
- Rewa · Loyalty Management
- Customised reward programmes
- Reward points and redemption accounts
- Points, cashback and tiers
Frequently Asked Questions
All of them, before money moves: transfers, ScanPay, cards online and in store, agent cash and merchant sales. Standalone and Super SDK banks run the same engine, and each bank’s rules and cases are kept apart from every other bank’s.
Launch the Future First
Launching a digital bank? Adding products to your app? Get your own mobile bank in your brand, or the UNIFOS Super SDK inside your app. Tomorrow’s banking, live today. Launch in weeks, on a revenue share.